Your Q2 appraisal cycle just wrapped up. Your star performer in the sales team is expecting her ₹45,000 performance bonus this month. Your payroll executive walks in and asks: “Do we add this to PF? What TDS rate applies? Can we pay it separately?” You realise your team doesn’t have a clean answer — and neither does your HRMS configuration. If this scenario sounds familiar, this guide is for you.
- Variable pay is fully taxable as salary — add it to annual income and deduct TDS at the employee’s applicable slab rate, including 4% cess.
- Performance-linked variable pay that differs employee-to-employee is excluded from PF basic wages (Supreme Court ruling; SC confirmed the “variable earning” exclusion).
- ESI applies if the employee’s gross salary — including variable — stays below ₹21,000/month in the month of payment.
- Under the Code on Wages 2019, if variable pay keeps allowances above 50% of total wages on a regular basis, EPFO can argue it’s part of “wages” — so structure carefully.
What is Variable Pay? A Working Definition for Indian HR
Variable pay is the portion of an employee’s compensation that changes based on individual, team, or company performance — as opposed to fixed pay, which stays constant every month. Variable pay is not the same as statutory bonus under the Payment of Bonus Act 1965. That’s a legal minimum you owe eligible employees whose salary is up to ₹21,000/month. Variable or performance pay is over and above that — it’s a discretionary (though often contractually committed) payment.
Common forms of variable pay in Indian companies include:
- Annual Performance Incentive (API) — typically 10–30% of CTC, paid once or twice a year
- Quarterly Performance Bonus — paid every quarter based on KPIs
- Sales Incentive / Commission — percentage of revenue or deals closed
- Retention Bonus — paid to key employees who complete a defined tenure
- Joining Bonus / Sign-on Bonus — one-time amount at joining
- Project Completion Bonus — common in IT, construction, and project-based work
How to Structure Variable Pay in Your CTC Design
The most common approach in Indian SMEs is to quote CTC as Fixed Pay + Variable Pay. For example, a ₹10 lakh CTC might break down as ₹8 lakh fixed (monthly payroll) and ₹2 lakh variable (paid quarterly or annually). This is fine in principle, but a few structuring decisions matter enormously for compliance.
The 50% Wage Rule Under the Code on Wages 2019
The Code on Wages 2019 defines “wages” to include all remuneration, but specifically excludes allowances (HRA, conveyance, etc.) that exceed 50% of total wages. Any excess is deemed wages and attracts PF contributions. While the Code’s full implementation is still pending state notification, EPFO is already using this logic to challenge payroll structures during inspections.
Practically: if you pay a ₹15,000 basic salary but a ₹20,000 monthly variable incentive, you’re in risky territory. Keep your fixed basic + DA at or above 50% of total monthly CTC to stay clean.
Should Variable Pay Be a Separate CTC Component?
Yes — always spell out the variable component clearly in the offer letter and employment contract. Use language like: “Annual CTC of ₹12,00,000, comprising ₹9,60,000 fixed and ₹2,40,000 variable, payable quarterly subject to performance targets as communicated by the management.” This clarity protects you legally and helps the employee plan their taxes.
TDS on Variable Pay — How to Calculate It Correctly
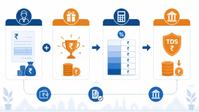
Variable pay is taxable as salary income under Section 15 of the Income-tax Act, 2025 (earlier Section 17 of the old Act, which governs income up to Assessment Year 2026-27). TDS is deducted at the employee’s applicable slab rate — not a flat rate. Here’s the process:
- Add the variable pay to the employee’s projected annual salary for the year.
- Reduce eligible deductions (standard deduction of ₹75,000 under the new regime, or 80C/80D etc. under old regime if they’ve opted in).
- Apply the applicable income tax slab, then add 4% Health & Education Cess.
- Back-calculate the additional TDS liability and either spread it across remaining months or deduct it in the month of variable pay.
FY 2026-27 Tax Slabs (New Regime — Default):
| Annual Income | Tax Rate |
|---|---|
| Up to ₹4,00,000 | Nil |
| ₹4,00,001 – ₹8,00,000 | 5% |
| ₹8,00,001 – ₹12,00,000 | 10% |
| ₹12,00,001 – ₹16,00,000 | 15% |
| ₹16,00,001 – ₹20,00,000 | 20% |
| ₹20,00,001 – ₹24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Budget 2026 retained these slabs unchanged. Employees earning up to ₹12.75 lakh effectively pay zero tax under the new regime (₹12 lakh basic threshold + ₹75,000 standard deduction). Variable pay that pushes someone above this threshold triggers tax on the marginal amount only — not the entire variable payout. Note: Form 16 is now referred to as Form 130 under the Income-tax Act, 2025.
One-Time Deduction vs. Spreading TDS
Two valid approaches: (a) deduct the full incremental TDS in the month you pay the variable bonus, or (b) spread the additional liability across the remaining payroll months. Most payroll software supports both. Option (b) is employee-friendly (smoother cash flow) but requires accurate projection of how much variable will be paid in which months. When in doubt, deduct fully in the bonus month — it’s cleaner.
PF on Variable Pay — What the Law Actually Says
This is where most HR managers get confused. The short answer: genuine performance-linked variable pay, which differs from employee to employee, is not included in PF wages.
The Supreme Court has confirmed (in cases including Bridge and Roof Co. vs. Union of India and subsequent rulings) that allowances or payments that vary based on individual performance and are not paid universally to all employees do not form part of “basic wages” under the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952.
However, EPFO inspectors will challenge you if:
- Everyone gets the same variable amount regardless of individual performance (i.e., it functions as a de facto fixed allowance)
- The variable component is mentioned in the appointment letter as a guaranteed amount
- You’re using variable pay as a workaround to artificially suppress basic wages and reduce PF liability
The safe test: if two employees with the same designation receive different variable amounts in the same month because one performed better, you’re fine excluding it from PF. If everyone gets ₹5,000 every month regardless, it’s a de facto fixed allowance and EPFO will include it in basic wages.
PF Rate Reminder: 12% of basic + DA (employee contribution) matched by employer at 12% — of which 8.33% goes to EPS (on wages up to ₹15,000 ceiling) and 3.67% to EPF.
ESI on Variable Pay — The ₹21,000 Threshold Rule
ESI (Employees’ State Insurance) applies to employees whose gross wages are below ₹21,000/month (₹25,000/month for persons with disabilities). The question is: does a one-time or quarterly variable payout push the employee’s gross above ₹21,000 in the month of payment?
If yes, ESI does not apply for that month. ESIC clarifications confirm that wages for ESI purposes include all regular payments, and a one-time bonus paid in a single month can exceed the ceiling temporarily without affecting ESI coverage for the rest of the year — as long as the employee’s regular monthly gross stays within ₹21,000.
Contribution rate: Employee pays 0.75% of wages; employer pays 3.25%.
Processing Variable Pay Through Payroll — A Step-by-Step Checklist
- Get the approved payout list — from the performance review system, approved by the department head and management
- Determine the payment month — run variable pay in the regular payroll cycle if possible, to keep TDS calculations clean
- Check ESI status — for each employee receiving variable, verify if their gross (including variable) crosses ₹21,000
- Calculate incremental TDS — add variable to projected annual income, recalculate liability, determine additional deduction
- Confirm PF exclusion is valid — ensure the variable amounts differ employee-to-employee (performance-linked)
- Update payslip — show variable pay as a separate earnings line item (“Performance Incentive” or “Quarterly Bonus”)
- Reflect in Form 130 (old Form 16) — ensure variable amounts are captured in Part A for the year
What HR Managers Get Wrong About Variable Pay
Mistake 1: Paying variable “outside payroll” to avoid TDS
Some companies pay variable bonuses through a separate bank transfer, skipping TDS. This is a compliance violation. All salary income — including variable pay — must go through payroll with proper TDS deduction. The Income Tax department’s system matches 26AS with Form 130 data; discrepancies trigger notices.
Mistake 2: Treating variable as guaranteed in offer letters
Writing “variable pay of ₹2,00,000 per annum” without a “subject to performance” qualifier creates a legal obligation. Employees have sued companies for non-payment. Always include: “payable basis achievement of targets as communicated.”
Mistake 3: Not separating statutory bonus from variable pay
The Payment of Bonus Act mandates minimum 8.33% bonus (up to 20%) on wages up to ₹7,000 or minimum wage — payable to eligible employees within 8 months of the financial year end. This is separate from performance bonus. Both must be tracked independently.
Mistake 4: Forgetting PT on variable pay
Professional Tax applies on gross wages in states like Maharashtra, Karnataka, West Bengal, Andhra Pradesh, Telangana, and Tamil Nadu. Variable pay is included in the month’s gross for PT calculation. PT slabs are state-specific — Maharashtra caps PT at ₹2,500/year.
Mistake 5: Assuming variable pay delays are legally fine
Once promised in the employment contract or letter, variable pay becomes a recoverable debt. Delaying payment beyond the agreed cycle can result in employee grievances and, in some cases, labour court claims.
FAQs: Variable Pay in India
Q: Is performance bonus the same as statutory bonus under the Payment of Bonus Act?
No. Statutory bonus under the Payment of Bonus Act is a legal minimum (8.33%–20% of wages up to ₹7,000) payable to all eligible employees earning up to ₹21,000/month. Performance bonus is a discretionary payment over and above this, based on individual or company performance. Both are taxable as income.
Q: If an employee leaves mid-year, do they get the variable pay for months worked?
This depends on your variable pay policy and the employment contract. If the policy says variable is payable pro-rata on exit, you must honour it. Many companies pro-rate variable for the months the employee was on roll. If the contract says variable is payable only to employees in service on the payment date, that can be enforced — but courts have occasionally ruled against “clawback” clauses that seem punitive.
Q: Should we process variable pay in a separate payroll run?
You can, but it’s cleaner to include it in the regular payroll month. A separate run makes TDS calculation harder and can create confusion in payslips. If you process separately, ensure your payroll software consolidates both runs for Form 130 (Form 16) purposes.
Q: What if our variable pay structure keeps changing — quarterly targets, different KPIs each quarter?
That’s fine. You don’t need to define exact targets in the offer letter — just state that targets will be communicated quarterly and variable pay will be calculated based on achievement. What matters is that you document the targets and payouts for each period, in case of disputes.
Q: Can sales incentives (commission) be excluded from PF?
If commissions vary month-to-month based on actual sales and differ from one salesperson to another, yes — they qualify for exclusion from PF basic wages under the Supreme Court’s variable earning test. If you pay a fixed “commission” regardless of sales, expect EPFO to treat it as basic wages.
Q: Our employee earns ₹18,000 fixed + ₹8,000 quarterly bonus in the bonus month. Does ESI apply?
In the month the ₹8,000 bonus is paid, gross = ₹26,000, which exceeds the ₹21,000 ceiling. ESI does not apply for that specific month. In all other months, gross = ₹18,000, so ESI applies normally. The employee’s ESI coverage remains active throughout the year.
If your payroll software can’t handle variable pay — split TDS calculations, PF exclusion logic, and quarter-wise payout tracking — it’s probably time for a system built for Indian compliance from day one. EZHRM’s payroll module handles variable pay, statutory bonus, and TDS calculations automatically, so your team spends time on HR, not spreadsheets.